

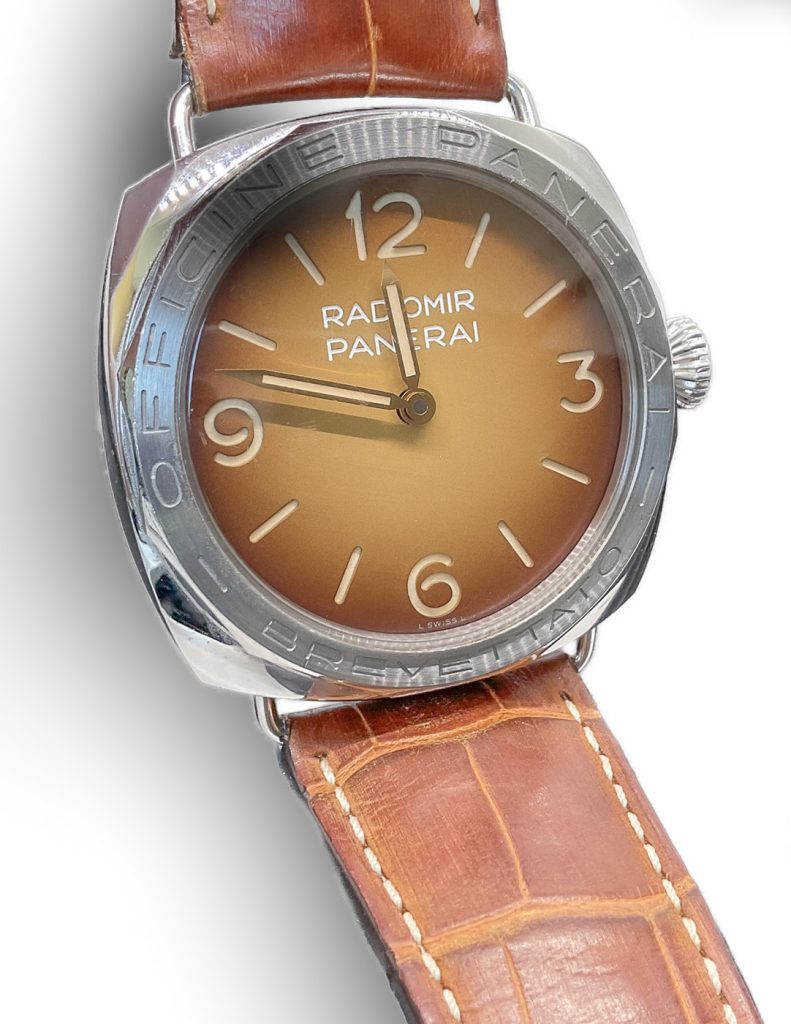
If you own a Panerai and need cash without parting with the watch, a collateral loan is worth understanding before you consider a sale. Unlike selling, a Panerai-secured loan lets you use the watch’s market value to get funds now while you keep the right to redeem the piece later. The details that matter most are how much of the watch’s value a lender will actually advance, what happens to the watch while it’s held, and how this kind of loan differs from a pawn shop transaction both legally and in cost.
How a Panerai-Secured Loan Works
A watch-secured loan is a straightforward transaction: a lender appraises your Panerai, offers a loan amount based on a percentage of that appraised value, and holds the watch as collateral until you repay. You aren’t selling the watch. You’re using it to secure short-term financing, similar in structure to a title loan on a car, except the collateral is a luxury asset instead of a vehicle. If you repay the loan according to its terms, the watch comes back to you. If you don’t, the lender keeps the watch and sells it to recover the loan amount, the same outcome a pawnbroker would pursue, but usually with better terms because the lender specializes in watches rather than general merchandise.
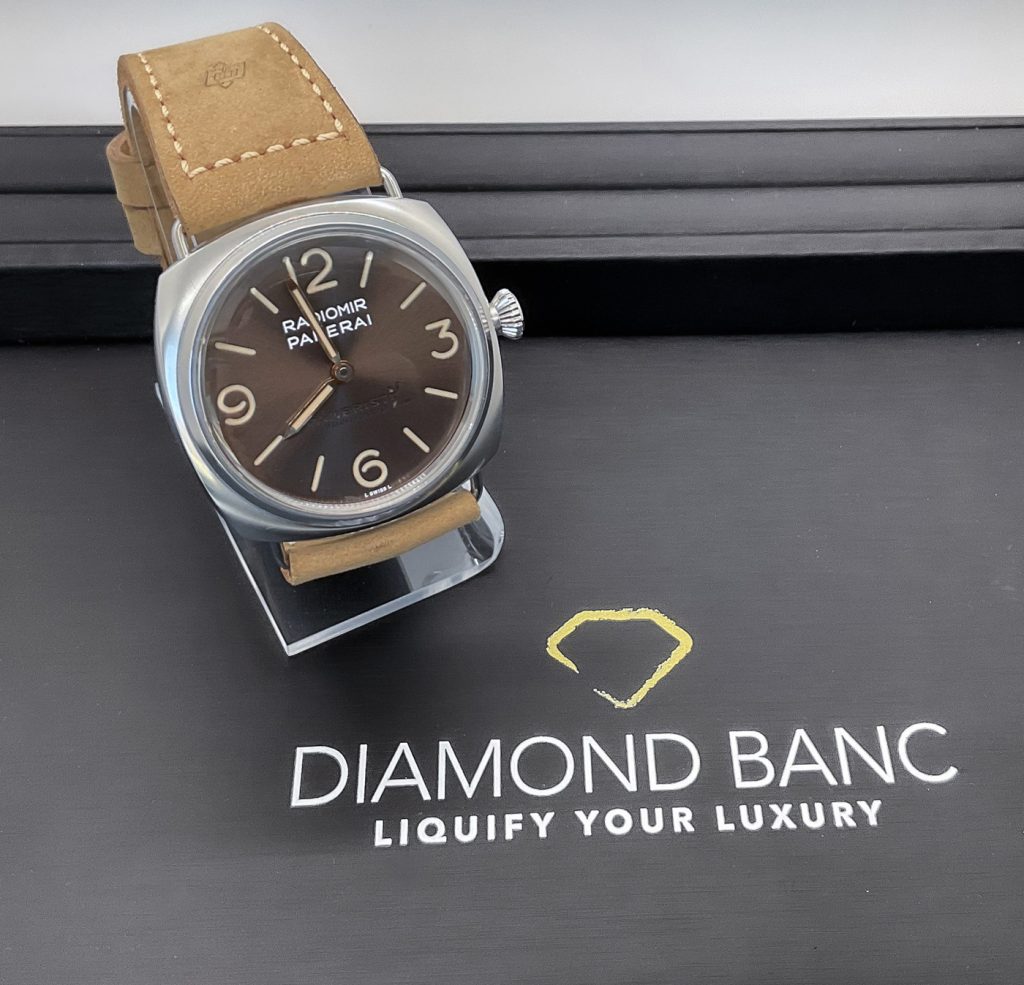
Diamond Banc issues loans secured by watches, and reference-specific valuation is central to that process. A Panerai Submersible and a Panerai Luminor Due are not treated the same way an unmarked “watch” would be at a general pawn counter; the model, reference number, condition, and documentation all factor into the appraisal before a loan amount is offered.
How Much of Your Panerai’s Value You’ll Actually Get
Lenders advance a percentage of appraised value, not retail price, and not what you originally paid. This loan-to-value ratio protects the lender against market swings and the cost of reselling collateral if a loan isn’t repaid. A conservative but realistic example: if a Panerai Submersible QuarantaQuattro 42mm appraises around $7,500 on the secondary market, a lender working off a 50% loan-to-value ratio would offer roughly $3,750 as the loan amount. That’s a useful baseline for setting expectations, since the number that matters is the appraisal, not the price tag you remember from the boutique.
Appraised value for a watch like this moves with the secondary market, so it’s worth checking current Panerai Luminor and Submersible secondary-market prices rather than assuming your watch is still worth what it cost new. For readers weighing a Panerai specifically, the Panerai page outlines what Diamond Banc looks for in an appraisal, and the general watch loans page covers how the loan process itself is structured.
Does Panerai Hold Enough Value to Make This Worthwhile?
This is the question Rolex owners rarely have to ask, and Panerai owners should ask upfront. New Panerai Luminor Marina models typically lose 20 to 30 percent of retail value in the first year and 30 to 40 percent over three years, a depreciation curve that’s notably steeper than Rolex or Omega. Part of the reason is production volume: Panerai makes roughly 70,000 to 80,000 watches a year, compared to Rolex’s approximately 1 million, which sounds like Panerai should be scarcer and therefore pricier on the secondary market, but the opposite tends to hold because Panerai’s collector base and resale demand are smaller relative to supply.
What this means practically: if your Panerai still has significant retained value (a well-kept Submersible or a desirable limited edition, for instance), it can absolutely work as loan collateral. If it’s a heavily discounted Luminor Marina several years off retail, the appraised value and resulting loan amount will reflect that depreciation honestly rather than your original purchase price. A lender who understands these distinctions by reference number, rather than treating “Panerai” as one undifferentiated category, will give you a more accurate number up front. That’s the difference between general pawn-shop appraisal and a specialist who prices model by model.
Panerai Loans vs. Pawn Shop Loans: The Legal and Cost Difference
Both a specialty watch-secured loan and a traditional pawn loan use your item as collateral, but the legal protections and costs differ. Federal Truth in Lending Act rules require any pawn ticket or asset-backed loan disclosure to clearly state the loan amount, finance charge, Annual Percentage Rate, total amount due to redeem, and the final due date, so you should expect that disclosure regardless of where you take the loan. What varies enormously is state law. Rate caps on these loans range from as low as 4% per month in New York to as high as 25% per month during the first 30 days in Florida, with Texas using a tiered system that can reach 20% per month on very small loan amounts. That means the actual cost of a loan secured by the same watch can differ sharply depending on which state issues it, and it’s worth reading the disclosure rather than assuming a rate quoted verbally is the final cost.
The other practical difference is expertise. A general pawn shop may lowball a Panerai because the staff isn’t equipped to distinguish a desirable reference from a discounted one, or because they default to scrap-value thinking on anything with a metal case. A lender built around luxury watches and jewelry, with access to current secondary-market comparables, is positioned to offer a loan amount that reflects what the watch is actually worth today, not a generic guess.
What Happens to the Watch While It’s Held as Collateral
Your Panerai doesn’t get serviced, altered, or worn while it secures a loan. It’s held exactly as received. That matters because Panerai’s own standard manufacturer warranty runs 24 months from purchase and is voided by any repair performed outside an authorized Panerai service center, so a reputable lender has no reason to touch the movement, the case, or the water resistance seals. If the watch needs anything, that’s your decision to make, on your timeline, after you’ve redeemed it.
This is also where pre-loan condition matters. Panerai recommends having water resistance checked roughly every two years, more often for watches used in diving, since gaskets age whether the watch is worn or sitting in a drawer. A watch that’s been unused and unserviced for several years may appraise lower simply because its condition can’t be verified without inspection, not because the model itself has lost desirability. If you know your Panerai hasn’t had a water resistance check in years, mentioning that upfront during appraisal avoids surprises in the offered loan amount.
Documentation That Changes What You’re Offered
Box, papers, and the original warranty card (particularly one signed by an authorized dealer) support a higher appraisal than a watch presented on its own. This isn’t unique to Panerai, but it matters more here than it might for a Rolex, because Panerai’s secondary-market premiums are already softer; full documentation is one of the few things an owner controls that can meaningfully improve the number a lender offers. If you registered for the Pam.Guard program, which can extend coverage up to 8 years for watches purchased within the past two years, bring that documentation too. It doesn’t change the watch’s physical condition, but it does support the story that the watch has been maintained through proper channels, which lenders and future buyers both weigh.
Keeping Ownership While Getting Cash
A loan does not transfer title to your Panerai the way a sale would. You retain ownership throughout the loan term and get the watch back once it’s repaid, which is the entire appeal for someone who needs liquidity now but isn’t ready to part with a piece they’d rather keep long-term. If you’re deciding between that route and an outright sale, it helps to compare both: Diamond Banc can structure a Rolex-secured loan for owners with Rolex pieces in a collection alongside Panerai, or you can sell a Rolex outright if that’s the better fit for a particular piece. For a broader look at how watch collateral loans work across brands, the guide to using a watch as collateral covers the general mechanics in more depth.
The decision ultimately comes down to what you need: short-term cash with the intent to redeem favors a loan; permanent liquidity with no plan to reacquire the piece favors a sale. Either way, getting an accurate, reference-specific appraisal first is what makes the rest of the decision easier.
Like what you’re reading?
Add us in Google — more like this is on the wayRelated Posts
 Instagram
 Facebook
 Tiktok
 YouTube